October 2, 2025

Bank vs. Agency Financing: A Comparative Guide

For sophisticated commercial real estate investors, securing the right financing is as critical as acquiring the right asset. The capital structure of a deal dictates everything from cash flow and returns to the level of risk exposure. Two of the most prominent sources of debt capital are traditional banks and government-sponsored enterprises (GSEs), commonly known as agency lenders. This guide is designed for experienced investors and developers to dissect the nuances of bank vs agency financing, helping you align your capital strategy with your investment objectives.

You will learn the key differentiators between these financing options, including their impact on interest rates, flexibility, and risk. Understanding this landscape is fundamental to optimizing your portfolio and making strategic financing decisions that propel your growth.

Understanding the Core Players: Banks vs. Agencies

At first glance, a loan is a loan. However, the source of that capital dramatically alters its terms, structure, and suitability for a given project. Think of it like choosing a vehicle for a cross-country race. A sports car might be faster on a straightaway, but a rugged off-road truck is better prepared for unpredictable terrain. Similarly, bank and agency loans are engineered for different purposes and market conditions.

Bank Financing

Originates from depository institutions like commercial banks, community banks, and credit unions. Their primary business is taking deposits and making loans. As portfolio lenders, they typically hold the loans they originate on their own balance sheets. This gives them significant discretion over underwriting and loan terms, but it also means their risk appetite can fluctuate with economic cycles and regulatory pressures.

Agency Financing

Provided by lenders who originate loans on behalf of government-sponsored enterprises (GSEs) like Fannie Mae and Freddie Mac. These agencies don’t lend directly to borrowers. Instead, they purchase qualifying loans from approved lenders, package them into mortgage-backed securities (MBS), and sell them to investors on the secondary market. This model provides a consistent and liquid source of capital for the multifamily housing market, but it requires strict adherence to standardized underwriting criteria.
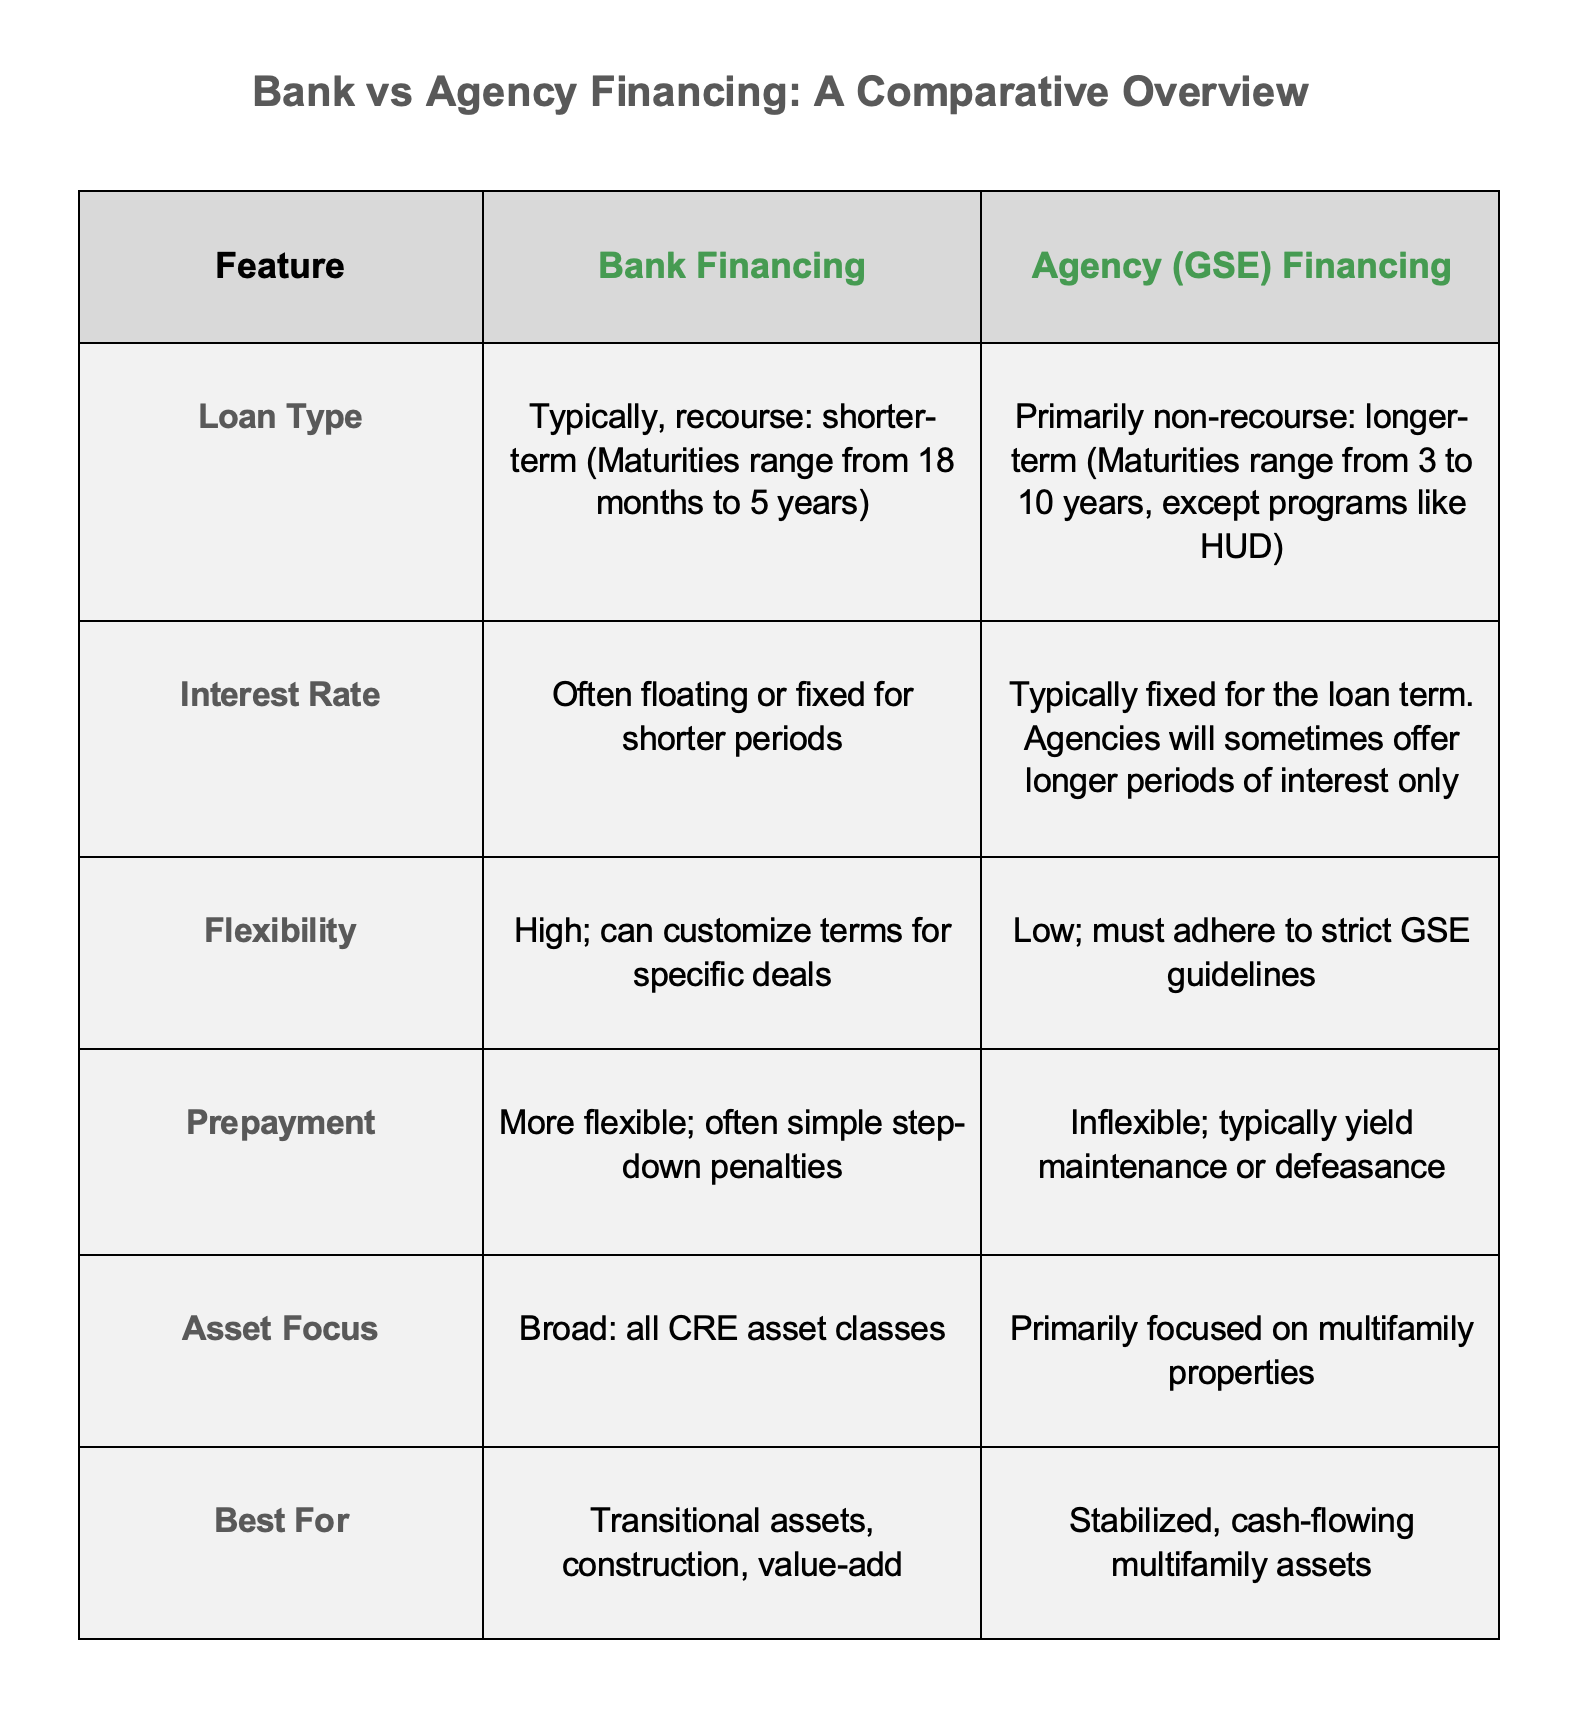
Key Benefits and Strategic Use Cases of Bank vs Agency Financing

Choosing between bank and agency financing depends entirely on the asset’s profile and your investment strategy. One is not inherently better than the other; they are simply different tools for different jobs.

When Bank Financing Excels in CRE

Bank loans are the preferred choice for investors seeking flexibility and creative structuring. Their ability to underwrite deals on a case-by-case basis makes them ideal for assets that don’t fit neatly into a standardized box.

  • Value-Add and Transitional Properties: Banks are more comfortable financing properties that require repositioning, renovation, or lease-up. They can underwrite based on a future stabilized value and may offer interest-only periods to accommodate the business plan.
  • Construction and Development: For ground-up construction or significant redevelopment projects, banks are the primary source of capital, offering construction loans that fund in draws as the project progresses. Banks are also more likely to offer interest only periods on transitioning assets or assets under development.
  • Diverse Asset Classes: While agencies focus almost exclusively on multifamily, banks will lend on office, retail, industrial, hospitality, and specialty properties.
  • Relationship-Driven Lending: A strong, established relationship with a bank can lead to more favorable terms and a smoother process, as the lender has familiarity with your track record and financial strength.

The trade-off for this flexibility is often a personal guarantee. Most bank loans are recourse, meaning the lender can pursue your personal assets if the property’s sale doesn’t cover the loan balance. They also tend to be shorter-term, creating future refinance risk.

When Agency Financing Is the Optimal Choice in CRE

Agency financing is the gold standard for long-term, stable acquisitions of multifamily properties. If your goal is to lock in favorable terms and minimize personal risk on a cash-flowing asset, an agency loan is often the superior option.

  • Long-Term Fixed Rates: Agency lenders offer long-term fixed-rate debt (up to 30 years), which eliminates interest rate risk for the life of the hold period. This predictability is invaluable for long-term investors.
  • Non-Recourse Structure: This is a major advantage. In a non-recourse arrangement, the borrower is not personally liable for the loan beyond the pledged collateral. Liability occurring in specific “bad boy” acts, such as fraud, gross negligence, or willful misconduct, as defined in the carve-out guaranty. Outside of these exceptions, a default on the loan does not trigger recourse to the borrower’s other assets or properties, thereby isolating risk and preserving the integrity of the broader portfolio.
  • Higher Leverage & Amortization: Both banks and agency lenders commonly offer 25- or 30-year amortization schedules, depending on the borrower’s profile and the deal structure. However, agency lenders may offer longer interest-only periods, particularly for stabilized assets or low-leverage transactions, making them attractive for maximizing early cash flow.
  • Capital Availability: Because agency loans are fueled by the secondary market, they provide a consistent source of liquidity that is less susceptible to regional economic downturns than bank lending.
  • Relationship-Driven: Agency lenders do place strong emphasis on the underlying asset’s performance, but they also consider the borrower’s track record and existing relationships, especially for repeat sponsors or those with strong portfolios.

The primary limitations are a lack of flexibility and significant prepayment penalties. Agency underwriting is rigid, and the property must meet specific criteria related to occupancy, debt service coverage, and physical condition. Early prepayment is costly, making these loans unsuitable for short-term holds.

A Step-by-Step Guide to the Process to Financing

While the goal—securing a loan—is the same, the path to closing differs significantly between bank and agency lenders.

The Bank Financing Process (Simplified)

  1. Initial Discussion: The process starts with a conversation with a loan officer. You present the deal, your business plan, and your financial background.
  2. Statements & Term Sheet: Submit due diligence documents (rent roll, operating statements, personal financial statements, etc.). The bank process typically begins after reviewing operating statements and a current rent roll. While banks may give preliminary verbal indications once materials are received, they rarely issue formal commitment letters.
  3. Underwriting & Credit Committee: The loan officer and an underwriter will analyze the deal and prepare a credit memo. This package is then presented to an internal credit committee review. This is where the bank’s internal discretion plays a major role.
  4. Commitment & Closing: Once approved, the bank will inform you that the loan has been approved. From there, you move to documentation and closing.


The Agency Financing Process (Simplified)

  1. Sizing and Quoting: You work with an approved agency lender who “sizes” the deal based on GSE guidelines for LTV, DSCR, and net operating income. They will then provide a quote with an interest rate based on current MBS market pricing.
  2. Application & Deposit: You sign the application and provide a deposit to cover third-party reports (appraisal, property condition assessment, environmental report).
  3. GSE Underwriting: The lender underwrites the loan according to the strict standards set by Fannie Mae or Freddie Mac. The file is then submitted to the agency for their review and approval. The agency has the final say.
  4. Rate Lock & Closing: Once the GSE issues a commitment, you can lock your interest rate. The process then moves to documentation and closing.


Key Takeaways: Making the Right Decision

The choice between bank and agency financing is a strategic decision that should be driven by your specific goals for the asset.

  • Recourse vs. Non-Recourse: Your tolerance for personal liability is a primary dividing line. Banks often require it; agencies offer non-recourse financing with the only liability coming in to play if certain fraudulent acts have occurred (a “carve-out” guaranty).
  • Hold Period: If you plan to sell or refinance in 3-5 years, a bank loan with a flexible prepayment structure is likely a better fit. For a 10+ year hold, the long-term fixed rate of an agency loan is highly attractive.
  • Asset Type & Condition: Is the property stabilized and cash-flowing, or does it require significant repositioning? Stabilized multifamily points to agency; value-add or non-multifamily assets point to banks.
  • Interest Rate Outlook: In a rising rate environment, locking in a long-term fixed rate with an agency loan can be a powerful defensive move. In a falling rate environment, a shorter-term bank loan may allow you to refinance into better terms sooner.


How Essex Capital Markets Provides Clarity

Navigating the complexities of bank and agency financing options requires deep market knowledge and strong lender relationships. At Essex Capital Markets, we serve as your strategic capital advisor, providing the expertise to structure the optimal financing solution for your deal.

We go beyond simply quoting rates. We analyze your asset and business plan to determine which capital source aligns with your objectives. Our extensive network includes both relationship-driven banks and top-tier agency lenders across the country. This allows us to create a competitive environment and secure expert-driven solutions tailored to your needs, ensuring swift decision-making and a streamlined closing process.

Final Thoughts

Ultimately, the right financing strategy is not about finding the lowest interest rate; it’s about finding the structure that best supports your investment thesis while mitigating risk. Whether the flexibility of a bank loan or the security of an agency loan is the right choice, a deep understanding of both options is essential for any serious commercial real estate investor.


Frequently Asked Questions: Comparing Bank vs. Agency Loans for Commercial Real Estate Investors

What is the main difference between bank and agency loans for commercial real estate?

Bank loans are typically more flexible and suited for short-term, transitional, or value-add projects, while agency loans offer long-term, fixed-rate, non-recourse financing for stabilized multifamily properties.

When should I choose a bank loan over an agency loan?

Bank financing is ideal for projects needing flexibility, such as construction, repositioning, or non-multifamily asset classes like office, retail, or industrial. They’re also preferable for shorter hold periods and investors comfortable with recourse.

When is agency financing the best option?

Agency loans are best for long-term holds of stabilized multifamily properties where you want fixed rates, non-recourse terms, and maximum leverage. They offer consistent capital but have stricter underwriting guidelines and significant prepayment penalties.

Are agency loans always non-recourse?

Yes, agency loans are generally non-recourse, meaning your liability is limited to the property itself. However, “bad boy” carve-outs can still apply in cases of fraud or misrepresentation.

Can I use agency financing for commercial properties that are not multifamily?

No, agency loans from Fannie Mae and Freddie Mac are primarily intended for multifamily assets. For retail, office, hospitality, or industrial properties, bank financing is the more suitable option.

How do interest rates compare between bank and agency loans?

Agency loans usually offer long-term fixed interest rates, making them attractive in rising rate environments. Bank loans may have floating or shorter-term fixed rates, offering flexibility in a declining rate environment.

What are the prepayment penalties for bank vs. agency loans?

Bank loans typically have more lenient prepayment terms like step-down penalties. Agency loans often use yield maintenance or defeasance, which can be costly if you plan to exit early.

How long does it take to close a bank loan vs. an agency loans?

Bank loans can close more quickly due to less standardized underwriting. Agency loans, while highly structured, may take longer due to GSE approval and required third-party reports. Essex Capital Markets helps streamline both processes.

Is a personal guarantee required for bank loans?

Most bank loans are recourse, meaning the borrower may be personally liable if the property’s value doesn’t cover the debt. In contrast, agency loans are non-recourse, offering greater protection to the borrower.

How can a capital advisor like Essex Capital Markets help me choose the right loan?

Essex Capital Markets evaluates your asset, investment strategy, and financial profile to match you with the ideal lender—whether that’s a relationship-driven bank or a top-tier agency lender—ensuring the best possible structure for your deal.


About Essex Capital Markets

Essex Capital Markets, LLC offers bespoke financing solutions and multifamily advisory services to mid-market investors and developers. The team specializes in structuring tailored debt strategies, navigating complex transactions, and delivering certainty of execution across Chicago’s most competitive real estate submarkets.


Ready to explore the optimal financing strategy for your next acquisition or refinance? Let us help you unlock your capital potential. To speak with our Capital Markets team, please fill out the form below.

News & Insights

Catch up on the latest company news and transactions. Explore the trends and ideas impacting the mid-market real estate financing and investment market.

Refinancing Options: Beyond Freddie Mac SBL

9.23.25

Unlocking Optionality: A Customized Financing Solution for a Prime Asset

9.13.24

Closing the Gap: Higher Proceeds Achieved for $850K Multifamily Financing in Logan Square

8.26.25

Strategic Execution for a Sponsor’s First Multifamily Acquisition

9.9.25

Executing Under Pressure: Refinancing a Sub-$1M Loan in Just 21 Days

3.3.25

Quick Execution, Better Terms: Cash-Out Refinance for Pilsen Multifamily Asset

5.5.25

Relationship-Based Refinance with Improved Fixed-Rate Structure in Chicago’s Ravenswood Neighborhood

10.29.25

Structuring Optimal Financing for Avondale Mixed-Use Property

11.11.24

Successful Andersonville Multi-Family Refinance: Essex Capital Markets Repositions an 8-Unit Asset for Better Terms and Faster Closing

11.18.25

Roscoe Village Freddie Mac Refinance Closes Seamlessly: Essex Capital Markets Secures Liquidity and Flexibility for Sponsors

11.4.25

Chicago West Town Regional Bank Refinance: How Essex Capital Markets Secured Lower Pricing and a Streamlined Non-Recourse Execution

11.11.25

Turning a Retail-Heavy Mixed-Use Asset Challenge Into a Cash-Out Refinance: Essex’s Strategic Market-Driven Approach

12.2.25

A Refinance Designed for Speed and Certainty | Portage Park Multifamily

1.22.26

Banks Are Tightening CRE Lending Standards. Where Are Borrowers Finding Capital

11.10.26

Essex Capital Markets Closes $73.4 Million Across 22 Transactions in Q3 2026

10.28.26

How a Quarter-Point Rate Increase Created a $6.8 Billion Multifamily Refinancing Gap

10.26.26

DSCR vs. Debt Yield vs. LTV: What Determines Your CRE Loan Amount?

10.21.26

Essex Capital Markets Secures $2.875 Million Cash-Out Refinance for Lake Bluff Multifamily Property

10.14.26

Essex Capital Markets Arranges $1.7 Million Cash-Out Refinance for Wicker Park Multifamily Property

10.14.26

Why Regional Banks Still Matter in Chicago CRE Lending

10.12.26

Essex Capital Markets Arranges $11.525 Million Refinance for Chicago Multifamily Portfolio

10.9.26

How 10 Basis Points Can Save $25,000 on a $5M CRE Loan

10.5.26

Essex Capital Markets Arranges $14.5M Recapitalization for River West Mixed-Use Property

9.30.26

Why the Lowest Interest Rate Does Not Always Mean the Besst CRE Loan

9.28.26

Fed Raises Rates 25 Bps: What Should CRE Borrowers Do Now?

9.21.26

Essex Capital Markets Arranges $1.91M Refinance for Avondale Multifamily Property

9.21.26

Essex Capital Markets Arranges $1.51 Million Acquisition Financing for West Town Multifamily Property

9.14.26

Bad-Boy Carve-Outs Explained: When a Non-Recourse CRE Loan Becomes Personal Liability

9.14.26

Essex Capital Markets Secures 74% LTV Financing for Logan Square Multifamily Acquisition

9.14.26

Essex Capital Markets Arranges $1.6 Million Refinancing for Five-Unit Lakeview Multifamily Property in Chicago

9.1.26

What DSCR Do Commercial Real Estate Lenders Actually Require in 2026?

8.31.26

The Questions That Matter Most in Today’s Lending Market

8.24.26

$65 Billion in CRE Loans Comes Due by Year-End. Is Yours One of Them?

8.17.26

Essex Capital Markets Arranges $2.66M West Town Land Acquisition Financing

8.11.26

Office to Residential Conversions: How We Underwrite the Opportunity

8.10.26

Essex Capital Markets Arranges $2.95M Acquisition Loan for 222 S. Morgan St.

8.6.26

Federal Reserve Holds Interest Rates Steady: What It Means for Commercial Real Estate Lending

8.3.26

Essex Capital Markets Arranges $6.3 Million Acquisition and Construction Loan for Albany Park Multifamily Property

7.29.26

When Does a Recourse Loan Actually Make Sense?

7.28.26

Essex Capital Markets Arranges $19.6 Million Acquisition and Construction Loan for River North Office Conversion

7.22.26

How Private Credit Is Changing Commercial Real Estate Lending

7.20.26

Essex Capital Markets Arranges $8.5 Million Lincoln Park Retail Refinance

7.15.26

5 Lending Trends We Observed From Our Q2 Chicago CRE Transactions

7.15.26

Essex Capital Markets Secures Strategic Refinancing for Four-Property Chicago Multifamily Portfolio

7.8.26

The Commercial Real Estate Refinance Process: What to Expect With Essex Capital Markets

7.6.26

Essex Capital Markets Structures Dual-Loan Financing Strategy for Bucktown and Roscoe Village Multifamily Properties

7.1.26

Choosing the Right Loan Structure for Your Commercial Real Estate Investment

6.29.26

East Lakeview Mixed-Use Property Receives Strategic Refinancing Through Essex Capital Markets

6.22.26

Treasury Rates vs. SOFR in Commercial Real Estate Financing

6.22.26

Is Your Maturing Loan a Problem or an Opportunity?

6.16.26

Essex Capital Markets Arranges Financing for West Town Multifamily Acquisition

6.8.26

Chicago CRE Financing Trends: Lessons From $15.4 Million of Closings

6.8.26

Rogers Park Mixed-Use Property Financing Arranged by Essex Capital Markets

6.2.26

Chicago Multifamily Supply Pipeline Remains Constrained in 2026

6.2.26

Essex Capital Markets Secures Financing for Lincoln Park Mixed-Use Property

5.27.26

Essex Capital Markets Secures Financing for Lincoln Park Mixed-Use Property

5.20.26

Pilsen Multifamily Asset Refinanced Through Essex Capital Markets

5.19.26

Chicago Multifamily Is Quietly Outperforming the National Market

5.18.26

Why Chicago CRE Borrowers Are Starting Refinancing Earlier

5.11.26

Essex Capital Markets Secures $2.95M Refinance for Palmer Square Multifamily Asset

5.11.26

What Is Actually Happening in Chicago CRE Financing Right Now

5.4.26

What We Watch Day to Day: The Micro Signals Driving CRE Financing Decisions

4.27.26

DSCR vs. LTV in Chicago CRE Financing: What Matters in 2026

4.20.26

What We Solved in Q1: 3 Lessons from Chicago CRE Financing

4.13.26

100 Days vs 30 Days. How Timing Impacts Your Financing Outcome

4.6.26

Essex Capital Markets Arranges $2.82M Acquisition Loan for 32-Unit Crown Point Asset

4.1.26

CRE Sentiment vs Reality in Chicago: What the Data Shows in 2026

3.30.26

77-Unit Pilsen Portfolio Refinance Completed with Local Bank

3.25.26

Regional vs National Banks in Chicago CRE Financing: How to Choose in 2026

3.23.26

Treasury Volatility Is Falling. What It Means for Chicago CRE

3.18.26

Essex Companies Complete Landmark Logan Square Transaction

3.11.26

$4.8M Acquisition Loan Secured for Rogers Park Multifamily Property

3.10.26

Refinancing Opportunities Emerging in Chicago CRE

3.9.26

Agency Lending Caps Rise for Chicago Commercial Real Estate

3.2.26

The Mid-Market Execution Gap in Chicago CRE | Monday Market Moves

2.23.26

Essex Capital Markets Delivers $20.8M Refinance for 90-Unit Lincoln Park Portfolio

2.18.26

How Chicago Lenders Are Underwriting Deals in 2026 | Monday Market Moves

2.16.26

Essex Capital Markets Secures $7.8 Million Bank Financing for Uptown Multifamily Asset

2.10.26

Chicago Commercial Real Estate Deal Volume Signals Renewed Lending Activity | Monday Market Moves

2.9.26

Commercial Real Estate Financing Questions for Chicago Owners in 2026 | Monday Market Moves

2.2.26

The Hidden Cost of Waiting in Today’s Capital Markets | Monday Market Moves

1.26.26

December Delivers: Essex Capital Markets Closes Over $23.9M in Final Month of 2025

1.20.26

What Lenders Are Looking for in Today’s Market and Why | Monday Market Moves

1.19.26

Multifamily Remains Chicago’s Most Financeable Asset | Monday Market Moves

1.12.26

Essex Capital Markets and Essex Realty Group Complete Addison Multifamily Financing and Sale

1.8.26

$15.5 Million Agency Refinance Completed by Essex Capital Markets for Logan Square Multifamily Portfolio

1.6.26

Capital Planning for Multifamily Owners Heading Into 2026 | Monday Market Moves

1.5.26

Essex Capital Markets Closes Bridge Financing for West Town Multifamily with Essex Realty Group

12.30.25

What Worked in 2025: Capital Strategies That Delivered | Monday Market Moves

12.29.25

Essex Capital Markets Arranges $2.5 Million Refinance for North Shore Multifamily Asset

12.22.25

What the 2025 Refinancing Wall Taught the Market | Monday Market Moves

12.22.25

Essex Capital Markets Executes $2.24 Million Cash-Out Refinance for 12-Unit Multifamily Portfolio

12.16.25

Stable Rates & Shifting Outcomes: Why Speed and Certainty Are Winning Deals | Monday Market Moves

12.15.25

Recourse vs. Non-Recourse Loans: Why It Matters in Commercial Real Estate

12.9.25

Multifamily Resurgence Signals Renewed Confidence | Monday Market Moves

12.8.25

Essex Capital Markets Secures Cash-Out Refinance for Logan Square Mixed-Use Property

12.2.25

Lenders Are Shifting Into 2026 Mode Earlier | Monday Market Moves

12.1.25

Stable Rates, Stricter Credit: Inside Year-End Lender Behavior | Monday Market Moves

11.24.25

Essex Capital Markets Secures Strong Terms and Smooth Closing for Andersonville Multifamily Asset

11.18.25

The Case for Refinancing Before Loan Maturity in Today’s Market | Monday Market Moves

11.17.25

Essex Capital Markets Secures Competitive, Non-Recourse Refinance for West Town Multifamily Property

11.11.25

Commercial Real Estate Lending Update | Monday Market Moves

11.10.25

Essex Capital Markets Arrange Strategic Freddie Mac Financing for Chicago Multifamily Property

11.5.25

Rates Stabilize, Refinance Momentum Builds Into Year-End | Monday Market Moves

11.3.25

Year-End Commercial Real Estate Refinance Trends | Monday Market Moves

10.27.25

Essex Capital Markets Arranges Competitive Refinance for Five-Unit Multifamily Property in Ravenswood

10.23.25

10-Year Treasury Slides Below 4% – Rate Relief or Economic Warning? | Monday Market Moves

10.21.25

Confronting the CRE Maturity Wall – Risks, Opportunities & Chicago Signals | Monday Market Moves

10.13.25

Bank vs. Agency Financing: A Comparative Guide

10.2.25

Asher Motew and Quinn Keenan of Essex Capital Markets Arrange Tailored Bank Financing for Roscoe Village Multifamily Asset

9.23.25

Essex Capital Markets and Essex Realty Group Partner on West Town Multifamily Sale and Financing

9.16.25

Essex Capital Markets Secures Financing for Bucktown Multifamily Property

9.10.25

Fed Meeting Looms, CRE Awaits Clarity | Monday Market Moves

9.1.25

Essex Capital Markets Arranges $850,000 Acquisition Loan for Logan Square Multifamily Property

8.28.25

Commercial Mortgage Brokers See Signs of Market Stability in 2025 | Market Monday Moves

8.25.25

Strategic Debt Solutions for Mid-Market Real Estate Investors in 2025

8.20.25

Interest Not “High” by Historical Standards | Market Monday Moves

8.18.25

CRE Lending Rebounds Strongly in Q2 | Monday Market Moves

8.11.25

Essex Capital Markets Promotes Quinn Keenan & Asher Motew to Director

8.8.25

Supplemental Loans: A Smart Way to Tap Equity Without Touching Your First Mortgage | Monday Market Moves

8.4.25

Finding Equilibrium: CRE Prices Flatten as Deal Volume Surges | Monday Market Moves

7.28.25

Multifamily: A Bright Spot in Commercial Real Estate | Monday Market Moves

7.21.25

Multifamily Momentum in CRE | Monday Market Moves

7.14.25

Impact of the 2025 “Big Beautiful Bill” on Commercial Real Estate | Monday Market Moves

7.7.25

Chicago Multifamily Market Update: Rent Growth, Capital Trends & Tax Relief | Monday Market Moves

6.30.25

Buying Commercial Real Estate Chicago: Market Signals | Monday Market Moves

6.23.25

Chicago Update: Multi Family Lenders & CRE Trends | Monday Market Moves

6.16.25

Chicago Multifamily Capital Markets Update | Monday Market Moves

6.9.25

Chicago Multifamily Market: Navigating Opportunities in 2025

6.4.25

CRE Loans Outlook & Market Strategy 2025 | Monday Market Moves

6.2.25

Essex Capital Markets Delivers $4.15M Acquisition Financing for Multifamily Property in Philadelphia

5.27.25

CRE Lending Outlook Amid Rate Volatility | Monday Market Moves

5.26.25

Commercial Real Estate Debt Outlook 2025 | Monday Market Moves

5.19.25

How Strategic Capital Is Shaping CRE in 2025 | Monday Market Moves

5.12.25

Essex Capital Markets Arranges Refinance for Multifamily Asset in Chicago’s Pilsen Neighborhood

5.7.25

Multifamily Financing Trends & CRE Capital Insights | Monday Market Moves

5.5.25

Why a Bridge Loan Might Make More Sense in Today’s Market

4.30.25

Navigating 2025’s CRE Landscape | Monday Market Moves

4.28.25

Market Trends & the Commercial Real Estate Capital Stack | Monday Market Moves

4.21.25

Chicago CRE and the Shifting Debt Landscape | Monday Market Moves

4.14.25

Essex Capital Markets Secures Loan for a 3-Unit Multifamily Property in Avondale

2.27.25

Essex Capital Markets Provides $59.1 Million in Fannie Mae Financing for Ten Lakeview Multifamily Properties

11.27.24

Essex Realty Group and Essex Capital Markets Close 18-Unit Mixed-Use Property in Avondale

11.11.24

Essex Capital Markets Secures $5.4 Million Loan for the Refinancing of Denver Multifamily Property

10.10.24

Is the Easy Way the Smart Way? Navigating Today’s Lending Environment

9.25.24

Steps to Effectively Prepare for a Maturing Loan

9.5.24

How The ECM Team Defines Creative Financing

8.8.24

Essex Capital Markets Closes $9.5MM Refinancing of Two Lakeview Multifamily Properties

8.6.24

Essex Capital Markets Closes 24-Unit Old Town Property

7.15.24

Essex Capital Markets’ Approach to Building a Capital Stack

7.3.24

Essex Capital Markets, LLC Appoints Elliott Quigley as New Managing Director

6.12.24

Refinancing Commercial Real Estate Properties with Essex Capital Markets: The ECM Process

5.28.24

Long vs. Short-Term Financing Amid High Interest Rates

4.26.24

Leveraging the 1031 Exchange: A Strategy for Chicago’s Multifamily Investors

4.10.24

Fixed or Variable Rate Mortgages: Strategic Insights for Real Estate Professionals

3.25.24

Economic Factors and Their Influence on Commercial Mortgage Trends

3.18.24

Navigating Commercial Mortgages in a High-Interest Rate Environment

2.23.24

Six Essential Reasons to Work with a Commercial Mortgage Broker

11.7.23

Essex Realty Group, Inc. Announces Launch of New Entity: Essex Capital Markets

10.22.23
VIEW ALL NEWS

CONTACT US
Essex Capital Markets, LLC
2718 W. Roscoe St.
Suite 100A
Chicago, IL 60618
Phone: 773.305.4900
Fax: 773.305.4901

MESSAGE US